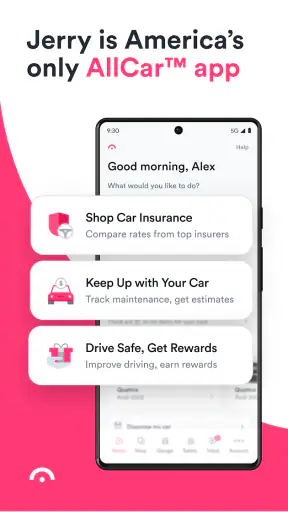
When I opened Jerry: Insurance & Car Care, I approached it less like a traditional insurance app and more like a practical starting point for the messy job of owning a car. The promise is appealing: help me compare car insurance, think through maintenance and repair costs, and potentially find discounts connected with safer driving. That combination makes sense because insurance is rarely an isolated decision. The premium, the condition of the vehicle, upcoming repairs, and driving habits all affect the real cost of keeping a car on the road.
My overall impression is that Jerry works best when I use it before a renewal, after buying a vehicle, or whenever I realize that my current insurance arrangement has simply continued by habit. It is free to use, aimed at everyone, and available on devices running a recent enough operating system. The developer is Jerry, Inc., and the app has built a sizeable audience, with more than a million installs and an average rating of 4.4 from roughly seventeen thousand ratings. Those figures suggest that many people find the approach useful, although they do not remove the need to check every quote and recommendation carefully.
From an expensive car question to a practical comparison
The starting condition for most users is probably familiar: a renewal notice arrives, a repair bill appears, or a newly purchased car needs coverage. In that moment, I do not necessarily need another place to read general insurance advice. I need to organize the facts about my vehicle and situation, compare realistic options, and understand what happens next.
That is where Jerry has a clear advantage over simply searching the web. A search engine can point me toward insurers, repair estimates, or driving advice, but it leaves the work of sorting everything out to me. Jerry brings those car-related decisions into one finance-focused app. The useful idea is not just “find a lower number.” It is to make the comparison happen while the details of the vehicle and its ownership costs are still in view.
I would begin by treating the app as a planning tool rather than assuming the first recommendation is automatically the right one. Before starting, I would have my current policy details, vehicle information, and preferred coverage priorities nearby. That small preparation matters. If I only care about the lowest monthly payment, I may overlook deductibles or changes in protection. If I need strong coverage because I depend on the car for work, a slightly higher quote may be the more sensible outcome.
The most important habit is to compare the whole policy, not just the headline price. A lower premium can be less attractive if it comes with a deductible I could not comfortably pay after an accident. Jerry can make the comparison easier, but it cannot decide what level of financial risk I am willing to accept.
Building the first comparison
The first part of the workflow is information gathering. I expect to answer questions about myself, my vehicle, and my existing insurance situation. This can feel routine, but it is also the point where accuracy has the greatest effect on the outcome. An incorrect vehicle detail, an outdated address, or an incomplete driving history can make a comparison less useful.
I would not rush through this stage simply because the app is designed to be convenient. The right approach is to pause whenever a question affects eligibility, coverage, or the estimated cost. A few extra minutes here are more valuable than receiving a polished comparison based on assumptions that do not match my real circumstances.
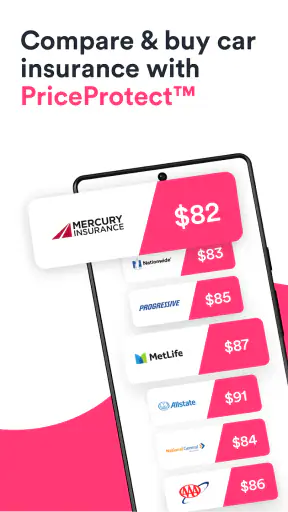
Once the information is entered, the app’s role becomes clearer. Instead of calling insurers one by one or filling out separate forms repeatedly, I can use one guided process to explore available insurance choices. That is a meaningful improvement for someone who dislikes administrative tasks. It is also useful when I am checking whether my existing policy is still competitive rather than automatically switching.
Still, convenience should not be confused with independence from insurers. The comparison process leads toward insurance providers and their offers, so the final terms remain important. I would read the coverage limits, exclusions, deductible, payment schedule, and cancellation details before agreeing to anything. The app can reduce the amount of searching, but it does not turn an insurance purchase into a one-tap decision.
Following the handoff from comparison to purchase
The handoff is one of the most important parts of this experience. Jerry can help me reach a suitable insurance option, but the insurer ultimately controls the policy documents, underwriting decision, billing, and claims process. That distinction is easy to miss when an app presents the journey in a smooth sequence.
In practical terms, I would use the comparison stage to create a shortlist. Then I would inspect each choice as if I were dealing directly with the insurer. Does the policy include the protection I need? Is the quoted amount based on information I entered correctly? What changes if I add another driver, move, replace the vehicle, or make a claim? These questions are not busywork. They are the difference between finding a genuinely appropriate policy and merely finding an attractive initial estimate.
This is also where the app may be less satisfying for users who want a single company to handle everything. Someone who prefers to speak with a familiar local agent may find the comparison workflow less personal. Jerry is more appealing to people who are comfortable reviewing choices digitally and taking responsibility for the final check.
For a first-time insurance buyer, I would recommend involving another person before accepting a policy if the coverage language feels confusing. The app can make the process more approachable, but insurance terms still have consequences that are not always obvious from a short summary. A family member, trusted adviser, or independent professional may be better placed to explain a complicated situation.
Using the car-care side after the policy decision
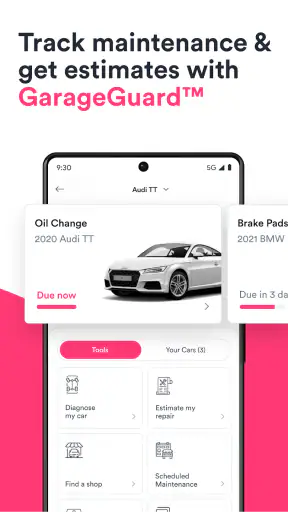
The second part of Jerry’s workflow is what makes it more distinctive than a basic insurance comparison service. Car ownership costs do not stop after I choose a policy. Maintenance and repairs can be just as disruptive to a monthly budget, especially when a warning light appears or a routine service turns into a larger job.
I see the car-care features as most useful when I use them before an emergency. If I wait until the vehicle has stopped working, I am likely to accept the first available repair option because I need the car immediately. If I use the app to think about maintenance and repair costs earlier, I have more time to compare the financial impact and decide whether a repair fits my budget.
A realistic example would be a commuter whose insurance renewal is approaching while the car is also due for service. Instead of treating those as unrelated expenses, I would use Jerry to review the insurance choice and then consider the upcoming maintenance cost. That combined view could reveal that a small monthly saving on insurance is less important than keeping enough cash available for the service. The app is valuable here because it encourages a broader ownership-cost conversation rather than focusing on only one bill.
There is a practical trade-off, though. A maintenance or repair cost estimate is a planning aid, not a final invoice. The actual amount can change after a mechanic inspects the vehicle and discovers additional work. I would use the app to prepare questions and set a rough budget, then ask the repair shop to explain labor, parts, urgent work, and optional work separately.
Where safe-driving discounts fit into the workflow
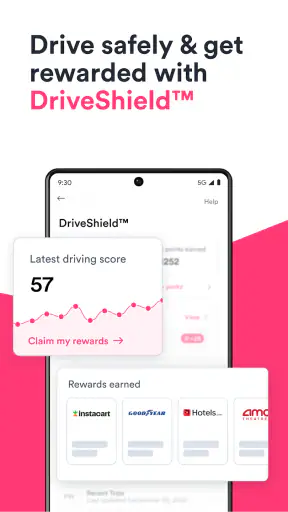
The safe-driving discount angle adds another possible handoff. If I am interested in lowering insurance costs through driving behavior, I need to understand that the benefit depends on how the relevant program evaluates driving and how an insurer applies the result. A discount is not the same as a guaranteed reduction for every driver.
This feature may suit someone who already drives carefully and is comfortable participating in a driving-based insurance process. It may be less attractive to a person who dislikes tracking, worries about how driving information is evaluated, or wants a completely predictable premium. Before opting in, I would look closely at the explanation presented in the app and at the insurer’s terms. The financial upside needs to be weighed against the user experience and any concerns about monitoring.
One non-obvious benefit is behavioral: the possibility of a discount can make me pay closer attention to habits such as hard braking, rapid acceleration, or distracted driving. Even if the eventual saving is modest, that feedback can encourage smoother driving. On the other hand, I would not change safe driving habits merely to chase a lower price while ignoring road conditions. Safety has to remain the priority.
What happens after I choose an option
The result of the workflow is not simply a quote on a screen. Ideally, I finish with a clearer understanding of the policy options, the likely effect on my budget, and the car-care costs that may arrive alongside the insurance bill. That is a better outcome than switching blindly, even if I decide to keep my current insurer.
I would save the policy documents and note the renewal date after completing a purchase. I would also keep repair estimates, service recommendations, and receipts in a separate place rather than assuming the app is my only record. This is a small but important workflow improvement: the app helps me make the decision, while my own records help me manage the consequences.
For households with more than one vehicle, the comparison can also be a useful prompt to review whether each car still fits its current role. A low-mileage second car, an older vehicle, and a primary commuter may not deserve identical coverage decisions. Jerry can help start that review, but I would still examine each vehicle separately instead of applying one preferred setting to every car.
People who are buying a used car may also benefit from this timing. Before finalizing the purchase, I would estimate insurance and likely maintenance costs together. A vehicle that looks affordable at the dealership can become much less attractive once coverage and repairs are considered. This is one of the strongest practical uses for the app: bringing insurance into the buying decision before the purchase is irreversible.
Where the flow breaks down
No comparison app can remove every source of friction. The first weak point is the amount of personal and vehicle information required. That is necessary for a meaningful insurance comparison, but it can feel intrusive or tiring, especially for someone who only wanted a quick general estimate. Users who are uncomfortable entering those details into a finance app may prefer contacting an insurer directly.
The second weak point is the risk of focusing too narrowly on price. A comparison interface naturally draws attention to numbers, and that can encourage users to choose the cheapest-looking option. I would treat the displayed cost as an invitation to investigate, not as the final answer. Coverage quality, claims experience, deductibles, and service expectations still matter.
The third issue is that insurance and car care are related but not identical services. Combining them is convenient, yet the handoff between finding information and acting on it may not always feel seamless. A repair estimate does not arrange the repair by itself, and a policy comparison does not replace the insurer’s support team. Someone looking for a full-service mechanic relationship or a dedicated insurance agent may find the app too focused on comparison and organization.
There is also a personal-fit question around safe-driving discounts. A careful driver who wants to explore every possible saving may appreciate the option. A driver who values privacy, dislikes app-based monitoring, or wants stable costs without behavior-based conditions may reasonably skip that part. The right choice depends on priorities, not on the existence of the feature alone.
Who should use it, and who should look elsewhere
I would recommend Jerry to drivers who are willing to compare rather than renew automatically, people buying a vehicle, households trying to understand total car costs, and anyone who wants insurance and maintenance considerations in the same place. It is especially practical for users who prefer a guided digital process over making several phone calls.
I would be more cautious about recommending it to someone with a highly unusual insurance situation, complicated ownership arrangements, specialized coverage needs, or a strong preference for a long-term personal agent. In those cases, direct conversations may produce clearer answers. Drivers who already have a carefully negotiated policy should also calculate whether switching is worth the administrative effort and any loss of established benefits.
The app is free, which lowers the barrier to trying the comparison workflow. It is rated for everyone, and its current version is 3.134.1, so users should keep the app updated on a compatible device. The product has been available since October 25, 2017, giving it a longer history than a newly launched finance tool, while its large user base indicates that the concept has reached well beyond early adopters.
My final take after following the full journey
Jerry is most convincing when I use it as a checkpoint in the ownership process: before renewal, before buying a car, before accepting a repair estimate, or before assuming that my current costs are unavoidable. It turns a scattered set of car expenses into a workflow that I can review in stages, from entering vehicle details to comparing insurance, considering maintenance, and checking the handoff to the companies that actually provide the service.
I would not use it as a substitute for reading policy documents, speaking to a mechanic about a serious fault, or deciding whether a safe-driving program fits my comfort level. Its value is in reducing the search burden and helping me ask better questions. For drivers who want a practical starting point rather than a completely hands-off answer, Jerry is a worthwhile free finance app to try.
My recommendation is to approach it with a simple rule: use the comparison to widen your choices, then slow down before committing. Check the coverage, verify the vehicle information, separate urgent repairs from optional work, and consider how each decision affects the rest of your budget. Used that way, Jerry feels less like a shortcut and more like a useful organizer for the real-world decisions that come with owning a car.


